

Nanobiotechnology Market Revolution: The $420 Billion Frontier Transforming Global Healthcare (2024–2034)

Market Size
Baseline & Run-rate
➤2024 revenue: US$ 172.81B
➤2025 revenue: US$ 289B (scale-up from COVID-era nano platforms, capital re-deployment, and new RNA/vesicle pipelines).
➤2034 projection: US$ 420.2B (CAGR 9.37%, 2025–2034).
Growth Math & Implications
➤Absolute dollar growth (2025→2034): US$ 131.2B added.
➤Implied 2024→2034 multiple: 2.43×.
➤Share leader (2024): North America 42%; APAC fastest through 2034.
Capital & Capacity Indicators
➤US biotech VC (2024): US$ 15.5B early-stage + US$ 7.6B late-stage (rebound toward pre-pandemic).
➤China R&D spend (2024): ¥3,632.68B; intensity 2.69% of GDP.
➤UK government R&I (2025–2026): part of £20.4B commitment via UKRI.
Market Trends
➤Lipid Nanoparticles (LNPs) lead: 34% share (2024) among platforms as LNPs power mRNA/siRNA delivery and next-gen vaccines/therapeutics.
➤Therapeutics pull-through: 38% share (2024) as nano-carriers improve targeting, dose, and safety.
➤Nano-formulated vaccines/therapeutics dominate products: 40% share (2024); continuous pipeline beyond COVID.
➤Instrumentation & Services fastest: Characterization, consumables, analytics, and software scale with QC/regulatory complexity.
➤Exosomes/biological vesicles fastest platform growth: Native vesicles enable low-immunogenic precision delivery.
➤Oncology the top therapy area: 34% share (2024) with nano-imaging, targeted payloads, and biomarker mapping.
➤Ophthalmology & localized delivery surge: Chronic eye disease burden + nano-carriers that extend residence time.
➤Buyer mix skews to pharma/biotech: 46% share (2024); CDMOs/CMOs fastest as manufacturing professionalizes.
➤Regional divergence: NA 42% today; APAC accelerates on hospital build-out, precision medicine, and private investment.
➤AI infusion: ML-guided design, automated characterization, and in-silico scale-up compress R&D cycles (see AI section).
10 AI Roles in Nanobiotechnology
➤Inverse design of nanocarriers: ML optimizes lipid/polymer compositions for stability, endosomal escape, and tissue tropism.
➤Multi-omics→payload mapping: AI links patient omics to nano-payload choice/dose for personalized delivery.
➤In-silico ADME/Tox of nanoparticles: Predicts biodistribution, protein corona formation, immunogenicity—cuts animal studies.
➤High-throughput image analytics: Vision models quantify particle size/shape, uptake, and subcellular localization from microscopy.
➤Quality by Design (QbD) automation: Real-time analytics + AI SPC flags drift in particle size/PDI/encapsulation during manufacture.
➤Exosome cargo selection: NLP + graph ML surface disease-relevant miRNA/mRNA cargo and targeting ligands.
➤Digital twins of nano-processes: Simulate microfluidic mixing, shear, and scale-up to industrial skids.
➤Clinical response prediction: Models correlate nano-PK/PD with outcomes to stratify responders and guide trial design.
➤Supply-chain optimization: Predicts lipid/excipient demand, lead times, and CDMO slotting to de-risk launches.
➤Regulatory documentation assist: AI assembles CMC, characterization, and comparability packages with audit trails.
Regional Insights
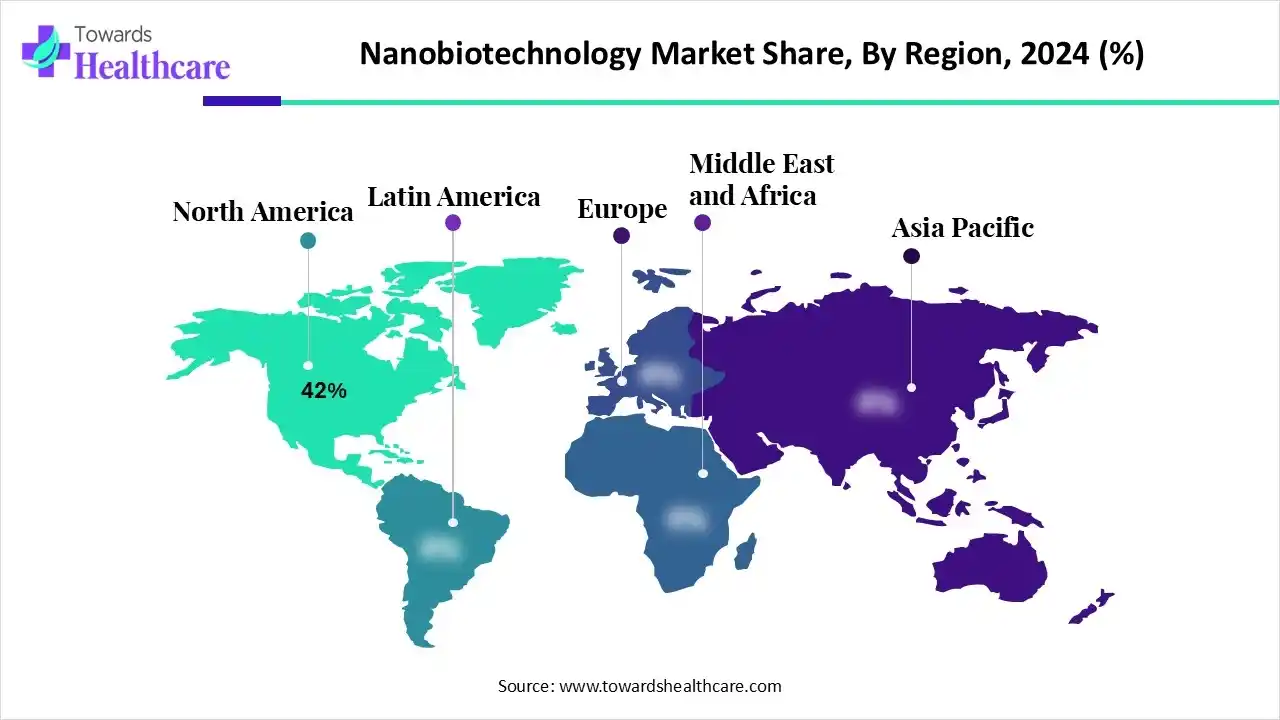
North America (42% share, 2024)
➤Strengths: Deep VC/IPO markets; established CDMOs; FDA guidance experience.
➤Focus areas: Oncology nano-combinations, RNA therapeutics, advanced analytics.
➤Outlook: Stable leadership; partnerships with APAC for cost-efficient scale-up.
Asia Pacific (fastest CAGR)
➤China
➤Drivers: ¥3.63T R&D; state programs; hospital expansion.
➤Themes: LNP inputs, exosome platforms, domestic characterization tools.
India
➤Drivers: CDMO/CMO capacity, cost-advantaged bioprocessing.
➤Themes: Nano-formulation services, generic-to-complex transitions.
Japan & S. Korea
➤Drivers: Materials science leadership, precision medicine adoption.
➤Themes: Inorganic nanoparticles, nanorobotics research, ocular delivery.
Europe
➤Drivers: UK/continental R&I ecosystems; strong QC/analytics vendors; EMA pathways.
➤Themes: Theranostics, GMP analytics, AI-assisted characterization.
➤Outlook: High-value niches; cross-border clinical networks.
Latin America & MEA
➤Drivers: Select hospital networks, academic hubs, and public initiatives.
➤Themes: Diagnostics access, targeted oncology imports, early CDMO footholds.
➤Outlook: Smaller base; opportunity in tech transfer and kits.
Market Dynamics
Drivers
➤Platform maturity: LNPs (34% share 2024) and exosomes enable new drug classes.
➤Clinical demand: Oncology (34% share 2024) and ophthalmology needs.
➤Capital flow: US VC US$ 23.1B (2024) combined; China R&D ¥3.63T; UKRI within £20.4B.
Restraints
➤Regulatory complexity: Particle heterogeneity and long-term safety datasets.
➤Manufacturing reproducibility: Tight control of size/PDI/encapsulation across scales.
➤Cost & supply: Lipids/excipients, single-use assemblies, and skilled labor constraints.
Opportunities
➤CDMO/CMO growth: Fastest buyer segment; turnkey nano-manufacturing and analytics.
➤Exosome therapies: Fastest-growing platform for immune-quiet delivery.
➤Software/analytics: Fastest product growth—AI QC, comparability, and release testing.
Challenges
➤Immunogenicity & corona effects: Patient variability impacts efficacy.
➤Cold-chain/logistics: Especially for RNA/LNP stability.
➤Talent gap: Nano/AI/regulatory tri-skill scarcity.
Top 10 Companies
Moderna
➤Product: mRNA therapeutics/vaccines using LNP delivery.
➤Overview: End-to-end mRNA platform from design to scale.
➤Strength: Rapid design-to-clinic, deep LNP IP, global manufacturing playbooks.
BioNTech
➤Product: mRNA oncology and vaccines (LNP).
➤Overview: Immunotherapy + RNA engine co-developed with pharma partners.
➤Strength: Personalized cancer vaccines, robust trial network.
Pfizer
➤Product: Comirnaty (with BioNTech), expanding nanoparticle therapies.
➤Overview: Big-pharma scale, late-stage dev and global distro.
➤Strength: Regulatory execution, supply chain, partnerships.
Acuitas Therapeutics
➤Product: LNP delivery systems licensed broadly.
➤Overview: Specialist IP/licensing powerhouse behind multiple RNA programs.
➤Strength: Best-in-class LNP chemistries and know-how.
Precision NanoSystems (PNS)
➤Product: NanoAssemblr microfluidic “nanoparticle factory.”
➤Overview: From R&D to GMP scale with reproducible mixing.
➤Strength: Scale-translatable platforms, ecosystem training.
Evonik / CordenPharma
➤Product: Lipids, excipients, and GMP manufacturing for RNA/LNP.
➤Overview: Materials + CDMO for critical lipids/supply.
➤Strength: Secure supply, specialized lipids, global plants.
Lonza / Catalent
➤Product: CDMO services for nano-therapeutics (fill/finish, analytics).
➤Overview: End-to-end industrialization partners.
➤Strength: Capacity, regulatory track record, tech transfer.
Thermo Fisher Scientific
➤Product: Characterization instruments, consumables, analytics software.
➤Overview: Tooling backbone for nano R&D/QC.
➤Strength: Portfolio breadth, installed base, service reach.
Merck / MilliporeSigma
➤Product: Lipids, single-use systems, nanoparticle analytics kits.
➤Overview: Materials + process solutions provider.
➤Strength: GMP supply chains, application support.
Nanobiotix
➤Product: NBTXR3 nano-radioenhancer.
➤Overview: Solid-tumor radiosensitization via inorganic nanoparticles.
➤Strength: Unique modality with combo potential in oncology.

Get a Sample of this Report
Nanobiotechnology Market
