

Optical Coherence Tomography Market Trends, Growth and Insights 2025

Market size
Baseline & trajectory
◉2024: US$ 2.26B
◉2025: US$ 2.62B (start of forecast CAGR 15.97%)
◉2034: ≈ US$10.0B
Implied year-by-year benchmarks (using 15.97% CAGR from 2025):
◉2026: US$ 3.04B │ 2027: US$ 3.52B │ 2028: US$ 4.09B │ 2029: ~US$ 4.74B │
◉2030: US$ 5.50B │ 2031: US$ 6.37B │ 2032: US$ 7.39B │ 2033: US$ 8.57B │ 2034: US$ 9.9–10.0B
Revenue composition (2024 snapshot):
◉Hardware systems: 64% of revenue (consoles/scanners, light sources, detectors, interferometers)
◉Software/AI & cloud analysis: fastest-growth stream (small base in 2024; highest CAGR through 2034)
◉On-premise device ownership dominated 2024 revenue; managed service/leasing rising fastest
◉Buyer concentration: Ophthalmology clinics & eye hospitals drove 70% of 2024 spend; cardiac labs accelerating (affects catheter/consumables pull-through)
◉Geographic mix (2024): North America 40%; APAC fastest-growing through 2034
Market trends
◉Disease-burden-driven demand: Growing glaucoma, AMD, and diabetic retinopathy prevalence propels OCT adoption for early, non-invasive, high-resolution diagnostics. WHO/CDC figures underscore large addressable populations and productivity loss from vision impairment.
Tech shifts inside OCT:
◉SD-OCT led 2024 (58% share) on speed/resolution;
◉SS-OCT is the fastest-growing on deeper penetration, faster scans, and better posterior segment/biometry use;
◉OCT-A gaining reimbursement traction and clinic uptake for functional microvasculature imaging.
◉Form-factor evolution: Desktop/table-top systems held 65% in 2024 (clinical workhorse), while portable/handheld platforms show fastest CAGR (point-of-care, outreach, tele-ophthalmology).
◉Beyond ophthalmology: Expanding cardiology (IV-OCT), dermatology, oncology, ENT/dentistry, preclinical—broadens TAM and mix of hardware+consumables.
◉AI infusion: Rapid shift to AI-assisted analysis, triage, and cloud reading to cut interpretation time, standardize quality, and enable scalable screening.
◉Business model innovation: From CapEx ownership toward managed service/device-as-a-service and subscription imaging, aligning costs with throughput; boosts adoption in smaller clinics and emerging markets.
◉Regulatory/reimbursement tailwinds: New CPT coverage (incl. OCT-A in many markets) + modular approvals (e.g., faster angiography acquisition) improve economics and workflow.
AI’s impact/role
Automated image interpretation & triage
◉Detects subtle retinal layer changes (e.g., RNFL thinning, drusen characteristics) and microvascular anomalies on OCT-A.
◉Benefits: earlier detection, lower miss rates, consistent reads across operators.
Disease staging & progression modeling
◉Longitudinal AI tracks per-patient trajectories (e.g., glaucoma progression rates, fluid dynamics in DME), quantifies treatment response, flags outliers needing regimen change.
◉Decision support in clinic workflow
◉Instant quality control, segmentation fixes, artifact suppression; auto-reporting to EHR cuts documentation time; enables higher patient throughput with the same staff.
Population screening & tele-ophthalmology
◉Edge-AI on portable OCT enables rapid community screening; cloud models support hub-and-spoke reading centers—key for APAC and remote regions.
Cross-modal fusion
◉Combines OCT with fundus/UWF, perimetry, labs, EHR for risk scoring; improves specificity for referral thresholds.
R&D acceleration
◉Foundation models trained on large OCT corpora power biomarker discovery, more precise clinical trial enrichment, and adaptive endpoints.
Cardiology IV-OCT
◉AI aids plaque characterization, stent apposition assessment, and procedure guidance in cath labs—shortens procedure time, improves outcomes.
Commercial implications
◉Shifts revenue growth toward software/AI subscriptions and cloud services; raises switching costs and deepens vendor lock-in; spurs data network effects.
Regional insights
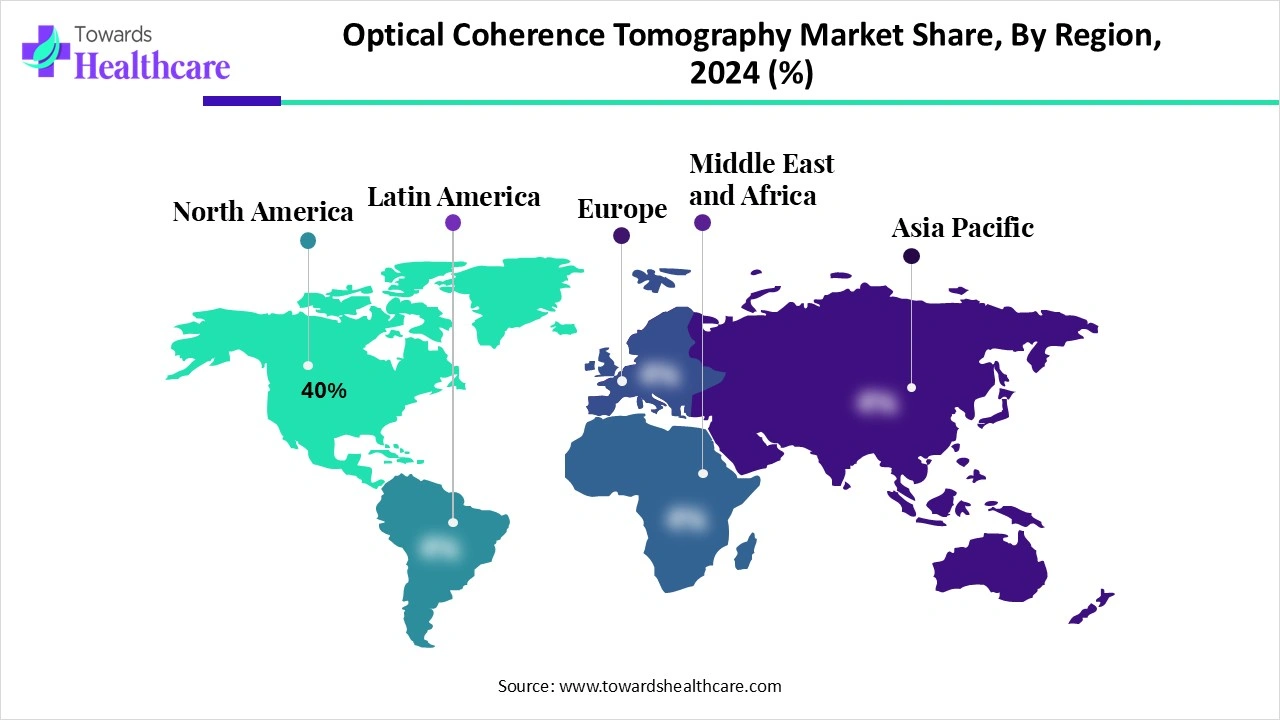
North America (40% share, 2024)
◉High-level: largest single market (≈40% of revenue in 2024). Mature payor systems, high clinical throughput, strong academic & vendor ecosystem.
Demand & clinical drivers
◉Aging population + disease burden: large cohorts with AMD, glaucoma, diabetic retinopathy drive recurring imaging and monitoring revenue.
◉Interventional cardiology adoption: IV-OCT used increasingly for PCI optimization — creates recurring consumable sales (catheters) and high-margin procedure-driven revenue.
Reimbursement & regulatory dynamics
◉Reimbursement maturity: Established CPT/insurance pathways for standard OCT and expanding coverage for OCT-A in many practices — improves economics for clinics to upgrade hardware and buy add-on modules.
◉Regulatory clarity: FDA pathways for AI/software have matured; cleared AI modules accelerate clinical adoption.
Product & tech priorities
◉High demand for premium desktop systems (throughput + integration).
◉Growing appetite for software/AI subscriptions — clinics willing to pay for time savings, triage tools, and validated decision support.
◉Cardiac IV-OCT bundles (console + catheter) perform well where hospital reimbursement covers intravascular imaging.
Channel, service & sales model
◉Direct sales + hospital procurement specialists dominate for high-end systems; distributor/partner model works for smaller regional practices.
◉Service contracts & SLAs are critical — quick on-site support, software updates, and training are differentiators.
Talent & workflow implications
◉Skilled operators & reading specialists are available, but AI reduces specialist bottlenecks and enables task-shifting to technicians.
◉Integration with EHRs and PACS is expected; interoperability is a procurement must-have.
Growth levers & go-to-market (GTM) tactics
◉Bundle hardware + subscription software + service to move purchases from CapEx to OpEx.
◉Emphasize FDA-clear performance and workflow KPIs (time saved, false positives reduced).
◉Target multi-specialty groups and academic centers for flagship deployments and peer-reviewed validation.
Risks & mitigations
◉Price sensitivity in community clinics: offer leasing/a-service.
◉Competition / consolidation: deepen service footprint and data features to increase switching costs.
Europe
◉High-level: mature clinical standards, strong research hospitals, varied national reimbursement and data-governance regimes.
Demand & clinical drivers
◉High standards of care and established ophthalmology networks; strong appetite for multi-modal imaging in tertiary centers.
◉SS-OCT adoption is accelerating in research hospitals and referral centers.
Regulatory & reimbursement environment
◉CE conformity provides market access but national reimbursement differs: some countries reimburse well for OCT-A/advanced imaging; others lag.
◉Data governance (GDPR) influences cloud usage and cross-border reads — limits some cloud-first models unless data residency and consent are solved.
Product & tech priorities
◉Multi-modal, research-grade systems favored in university hospitals.
◉Interoperable software and strong data-privacy controls are procurement musts.
Channel & service
◉Tender-driven procurement for many public hospitals — requires long lead time and strong evidence dossiers.
◉Local distributors used in many markets; after-sales service quality is often a buying differentiator.
GTM & sales tactics
◉Clinical publications and local KOLs drive adoption — invest in clinical studies and peer engagement.
◉Country-specific reimbursement strategies (e.g., pilot programs for OCT-A) help uptake.
Risks & mitigations
◉Fragmented reimbursement — map country-level payor policies and prioritize markets with favorable coverage.
◉Data residency constraints — provide localized cloud options and on-premise software.
Asia-Pacific (fastest growth)
◉High-level: highest CAGR prospect; huge population exposure (China, India) plus technologically advanced pockets (Japan, South Korea). Wide heterogeneity — from high-end hospital demand to mass screening needs.
China
◉Market posture
◉Large patient pool (high diabetes prevalence) and aggressive government screening programs expand TAM quickly.
Pricing & partnerships
◉Local–global partnerships and OEM manufacturing reduce ASP and accelerate scale.
Adoption models
◉Mass screening + AI triage programs in community clinics and county hospitals.
GTM & operational needs
◉Localization (language, workflow), local regulatory approvals, and strong local support are essential.
Opportunity & risk
◉Opportunity: scale via national screening programs.
◉Risk: price competition and need to localize AI models.
Japan
Market posture
◉High per-capita spend, advanced hospitals, homegrown leaders (Topcon, Canon) influence standards.
Tech appetite
◉Rapid SS-OCT adoption and premium product demand; strong IV-OCT use in cardiology.
GTM
◉Domestic partnerships & clinical validation with Japanese institutions accelerate uptake.
India & Southeast Asia
Market posture
◉High unmet need plus constrained budgets — ideal for portable OCT and tele-ophthalmology.
Adoption models
◉NGO/government screening creates demand for low-cost portable units; leasing enables procurement.
Operational constraints
◉Training, maintenance, and connectivity are key execution risks.
GTM
◉Partner with eye-care NGOs and public programs; offer service bundles and remote training.
APAC GTM & Strategy (overall)
◉Two-track product strategy: premium desktop + affordable portable/managed-service portfolios.
◉Invest in local regulatory & training centers to build trust.
◉Design AI models for local populations (ethnic/retinal variance) to avoid performance gaps.
Latin America
◉High-level: emerging commercial adoption led by urban private clinics; price sensitivity and fragmented reimbursement.
Demand & drivers
◉Private ophthalmology chains and tertiary centers lead purchases; preventive screening rising in urban centers.
Barriers
◉Budget constraints, inconsistent reimbursement, and service/parts logistics limit rapid spread.
Product & service fit
◉Refurbished units, lower-cost SD-OCT, and leasing models succeed.
GTM & channel
◉Local distributors with strong service networks are essential; warranty + training is persuasive.
Opportunity
◉Bundle solutions (hardware + remote reading + training) to overcome specialist shortages.
Middle East & Africa (MEA)
◉High-level: heterogeneous — GCC (wealthy hubs) vs. Sub-Saharan Africa (resource constrained). Medical tourism hubs create pockets of premium adoption.
Demand segmentation
◉GCC centers invest in high-end systems; sub-Saharan markets need portable, low-cost screening solutions.
Constraints
◉Skilled operator scarcity and long supply chains for parts/maintenance.
Product & GTM fit
◉Portable OCT + cloud reading to bridge specialist gaps; service partnerships for uptime are critical.
Strategic plays
◉Pilot programs with international NGOs and tele-reading centers; supply modular service agreements.
Risk mitigation
◉Local training programs and spare-parts depots reduce operability risk.
Cross-regional tactical recommendations
Segment GTM by clinic tier
◉Tier-1 (academic & hospital systems): sell premium integrated desktop SS-OCT + research partnerships.
◉Tier-2 (regional clinics): offer mid-range SD-OCT + managed service lease.
◉Tier-3 (rural/outreach): portable OCT + AI triage + cloud reading.
Monetize software & data
◉Offer AI-enabled subscriptions, outcome dashboards, and imaging-as-a-service to shift toward recurring revenue; provide on-premise/cloud options per region.
Localize AI & regulatory dossiers
◉Train & validate AI on regional datasets (APAC, Latin America) to ensure performance and regulatory acceptance.
Service network as moat
◉Invest in local service centers, spare parts, and training academies—especially in APAC, LatAm and MEA.
Flexible pricing
◉Introduce leasing, managed service, pay-per-scan, and refurbished routes to accelerate penetration in cost-sensitive markets.
Build clinical evidence
◉Sponsor local clinical studies and generate country-specific economics (e.g., screening ROI) to support tenders and reimbursement conversations.
Market dynamics
Drivers
◉Rising ophthalmic & chronic disorders: Large prevalent/at-risk pools; e.g., millions affected by glaucoma/DR; WHO notes 2.2B with vision impairment globally and US$411B in annual productivity loss.
◉Tech advancement: SD-OCT dominance (2024), SS-OCT fastest growth, OCT-A uptake, higher resolution, faster acquisition, better segmentation.
◉AI integration: Accuracy, speed, workflow relief; unlocks screening and remote models.
◉Broader indications: Cardiology (IV-OCT), dermatology, oncology, ENT/dentistry, preclinical.
Restraints
◉Skilled personnel needs for acquisition/interpretation;
◉Reimbursement gaps in certain countries;
◉Deep-tissue limitations and artifacts in specific conditions.
Opportunities
◉Favorable regulatory & reimbursement (new CPTs; modular approvals, incl. angiography);
◉Managed service/leasing to penetrate smaller clinics/emerging markets;
◉Cloud reading/tele-ophthalmology to scale access;
◉AI-enabled population screening reducing specialist bottlenecks.
Top companies
Carl Zeiss Meditec (incl. Optovue)
◉Products: Broad SD-OCT/SS-OCT portfolio; angiography; integrated software suites.
◉Overview: Pioneer with deep install base in ophthalmology; strong hardware–software integration.
◉Strengths: Image quality, workflow tools, expanding AI/analytics, global service.
Heidelberg Engineering
◉Products: Spectralis platform with OCT-A; SHIFT tech (faster OCT-A acquisition).
◉Overview: High-end retinal imaging; research-grade performance crossing into routine care.
◉Strengths: Robust segmentation, longitudinal tracking, academic trust, recent OCT-A speed enhancements.
Topcon Healthcare
◉Products: SD/SS-OCT systems; data management; new data-as-a-service initiatives (IDHea).
◉Overview: Strong in Asia-Pacific and global eye-care networks.
◉Strengths: Value-to-premium coverage, connectivity, growing digital health layer.
Canon Medical Systems / Canon (incl. Tomey units)
◉Products: Ophthalmic OCT systems; imaging ecosystem integration.
◉Overview: Imaging pedigree; Japan leadership.
◉Strengths: Reliability, optical engineering, hospital integration.
NIDEK
◉Products: Clinical OCT systems integrated into broader ophthalmic workflow.
◉Overview: Cost-effective clinical solutions.
◉Strengths: Installed base in clinics; service network in Asia.
Haag-Streit / Leica Ophthalmic
◉Products: Premium ophthalmic imaging/surgical visualization; OCT integration.
◉Overview: Operating-room and clinic presence.
◉Strengths: Optics quality, surgical ecosystem links.
Thorlabs / Wasatch Photonics / Santec / Lumedica (components & systems)
◉Products: Light sources, spectrometers, interferometers; research/industrial OCT kits.
◉Overview: Enable R&D and OEM supply.
◉Strengths: Customization, innovation cadence, academic relationships.
Abbott / Terumo / Boston Scientific / Philips (intravascular OCT)
◉Products: IV-OCT consoles, catheters, and integration for cath labs.
◉Overview: Interventional cardiology heavyweights.
◉Strengths: Procedure integration, consumables pull-through, extensive clinical evidence and field support.

Get a Sample of this Report
Optical Coherence Tomography Market
