

Pharmaceutical Packaging Market Size, Growth and Latest Insights 2025

Market Size
◉2023 Market Value: US$ 139.40 billion
◉2034 Market Value: US$ 387.50 billion
◉CAGR (2024–2034): 9.74%
◉North America (2023 share): 36% of global revenue
◉Europe: Growing steadily, driven by biologics & eco-friendly innovations.
◉Asia Pacific: Fastest-growing region due to government investments, patient pool, and strong pharma base (China & India lead).
◉Latin America: Brazil & Mexico driving growth due to rising pharmaceutical exports.
◉Middle East & Africa (MEA): Emerging opportunities due to increased import dependency on pharma products.
Market Trends
Primary packaging supremacy + speed
◉Dominated 2023 and remains the fastest-growing product class: vials, ampoules, prefilled syringes, bottles, blisters.
◉Catalyst: surge in biologics/vaccines and sterile injectables.
Plastics & polymers = workhorse materials
◉2023 leader by material due to cost, weight, manufacturability; PVC, PET, PE, PP, PS central across bottles, blisters, closures, device housings.
Paper & paperboard acceleration
◉Significant growth outlook: sustainable secondary & tertiary packs, plus novel primary-adjacent concepts.
◉Example given: Push-Pak (Keystone, Jun 2024) → compact paperboard blister concept optimizes footprint.
Injectables outrun all drug-delivery modes
◉Fastest 2024–2034 CAGR due to biologics, GLP-1s, and complex therapies needing sterile, barrier-strong, device-integrated packs.
Smart/secure packaging mainstreaming
◉RFID/NFC/QR/holograms → anti-counterfeit, traceability, adherence.
◉IoT tie-ins for cold chain assurance and last-mile visibility.
Generics volume flywheel
◉Lower price points → higher SKU volumes → sustained demand for cost-optimized primary + secondary formats.
◉Your data point: Teva generic revenue US$ 8.734B (2023) and pipeline scale underline generic-led packaging volumes.
Circularity & recyclability inflection
◉CiPPPA (UK, Apr 2024) targets end-of-life recycling pathways.
◉Aluflexpack 4Form (Jul 2024) single-material lacquered aluminum blister.
◉SGD Pharma (Sep 2024) PCR glass campaign in China.
AI’s Impact
Quality & Compliance
◉Machine vision detects dents, cracks, misprints, fill-level anomalies; reduces escapes to near-zero at line speed.
◉Real-time SPC + AI drift detection flags subtle pattern shifts (seal integrity, torque variability), preventing batch rework/recall.
◉Example from your data: Sea Vision Group (Dec 2023) AI to elevate packaging quality/productivity.
Throughput & OEE
◉Predictive maintenance models for cartoners, blister thermoformers, vial washers/fillers → fewer unplanned stops; higher OEE.
◉Dynamic scheduling: AI re-sequences lots to minimize changeover, balancing sterilization windows & expiry constraints.
Material/Design Intelligence
◉AI-driven finite element & barrier simulations: optimize wall thickness, blister cavity geometry, headspace O₂ control → material savings without risking stability.
◉LCA optimizers: weigh CO₂e, recyclability, and cost under regulatory constraints (e.g., child-resistance, tamper-evidence).
Serialization & Anti-Counterfeit
◉AI cross-validates serials across line/cloud, detects copy/clone patterns, and triggers investigations.
◉Computer vision for microtext/hologram authenticity in QA sampling.
Cold Chain & Smart Packaging
◉Sensor data (temp/humidity/shock) + AI identifies route-risk corridors, anticipates excursions, and recommends packaging insulation upgrades or lane changes.
◉Adherence analytics (smart blisters) → insights for patient programs (pharma-sponsored), feeding demand planning.
Cost & Waste Reduction
◉Yield analytics pinpoint scrap sources (forming film wrinkles, label misfeeds).
◉Digital twins model new lines: avoid over/under-spec of capital.
Governance & GxP
◉AI audit trails & explainability layers structured for CSV (computer system validation) and data integrity expectations.
◉Bottom line: AI defends quality, cost, and speed simultaneously, and is decisive for injectables & smart pack success.
Regional Segments
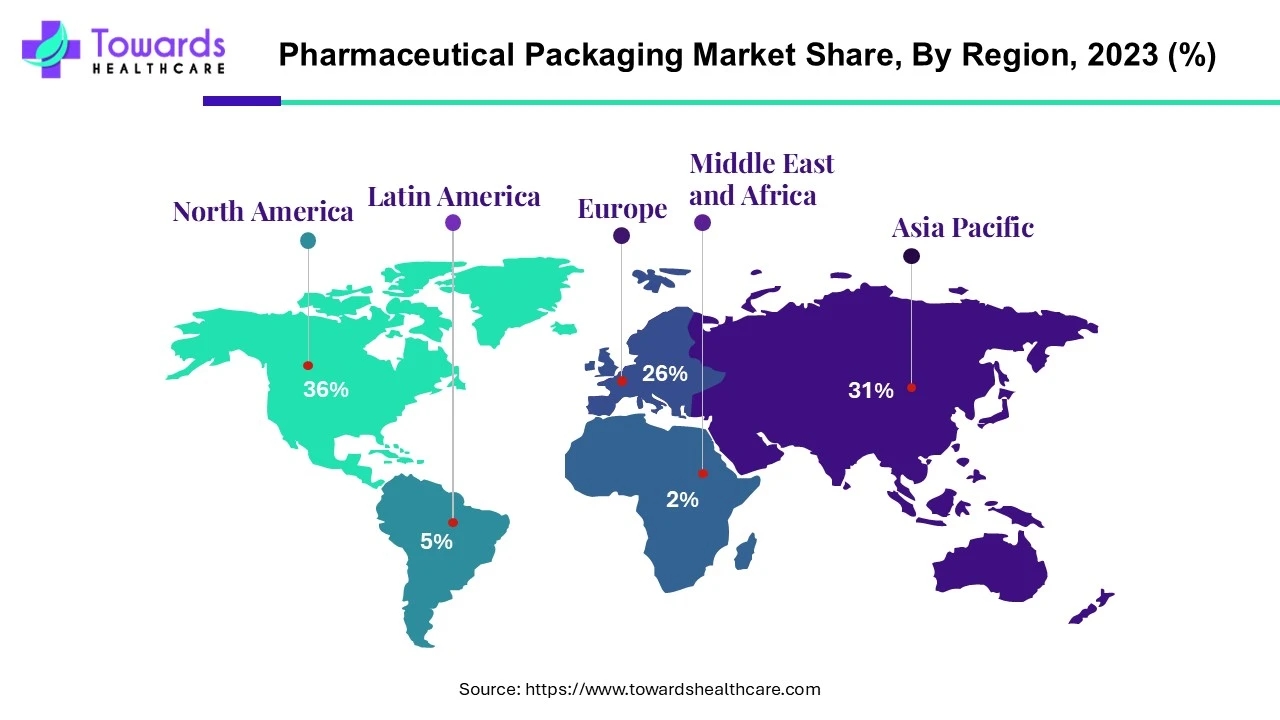
North America (NA) — 36% share in 2023 (US$ 50.18B)
◉Demand engines: high prevalence of chronic disease; strong biologics & GLP-1 pipelines → vial/syringe/blister intensity.
◉Infrastructure: large base of CDER-recognized manufacturing sites; pharma maintains in-house primary packaging + validated suppliers.
◉What wins: compliant sterile containment (Type I glass, advanced elastomer closures), CR/SF (child-resistant/senior-friendly) Rx packs, robust serialization.
Asia Pacific (APAC) — Fastest growth
◉China: largest API producer; “Made in China 2025” → upstream self-reliance, downstream premiumization; PCR glass initiative (SGD) shows sustainability tilt.
◉India: 20% global generics share; ₹4,17,345 Cr (2023–24) pharma turnover → blister, bottle, strip packs at scale; value-engineering + compliance are key.
◉Japan/Korea: device-integrated injectables, high-precision prefilled syringes; demand for tight tolerances and cleanroom packaging.
Europe
◉Biologics/biosimilars drive temperature- & light-sensitive containment; thermo-protective primary packaging R&D (notably Germany).
◉Circularity: CiPPPA (UK) aligns value chain on end-of-life solutions; push for mono-material and recycled content (SGD PCR glass).
◉What wins: glass excellence, barrier films, re-processable formats, documented eco-footprint.
Latin America
◉Brazil/Mexico: rising pharma manufacturing and exports → formalization of GMP-compliant packaging supply, serialization adoption.
◉What wins: cost-efficient yet compliant secondary/tertiary packs, reliable cold-chain for biologics importation.
Middle East & Africa (MEA)
◉Import-led pharma consumption; expanding healthcare spend and specialty imports ⇒ demand for robust tertiary + insulated shippers.
◉What wins: validated cold-chain kits, counterfeit-resistant features, regional last-mile resilience.
Market Dynamics
Demand drivers
◉New medications (biologics, vaccines) → stringent primary containment.
◉Rising transportation volumes → reliable/sustainable packaging to defend against temperature, light, moisture, shock.
◉Biodegradable & eco-innovations → accelerate paper/paperboard & mono-material blisters.
Restraints
◉Strict regulation (patient safety, tamper-evidence, labeling, sterility).
◉Counterfeiting risks → added cost/complexity (serialization + smart features).
Opportunities
◉Smart packaging (hologram/NFC/RFID/QR) for track & trace and patient engagement.
◉Injectables outperformance (fastest-growing delivery mode 2024–2034).
◉Recycling initiatives (CiPPPA) and PCR materials (SGD) enable differentiated sustainability.
Risks & mitigations
◉Material volatility → dual-source critical films/resins; design for material substitution.
◉Regulatory change → proactive change control and modular packaging.
◉Counterfeit escalation → tiered security (overt/covert/forensic) + analytics.
Leading Companies 2025
Amcor plc — Global converter
◉Products: Flexible/rigid pharma formats (primary films, pouches, blisters; secondary cartons).
◉Strength: Scale + sustainability programs; broad GMP footprint.
WestRock Company — Fiber systems leader
◉Products: Paperboard cartons, CR/SF designs, inserts/leaflets.
◉Strength: Structural design, converting scale, sustainability credentials.
Berry Global, Inc. — Plastic systems
◉Products: Bottles, closures, specialty components for pharma.
◉Strength: High-volume polymer conversion, closure systems.
Owens-Illinois (O-I) — Glass containers
◉Products: Glass bottles/containers (pharma-use SKUs exist).
◉Strength: Glassmaking scale, barrier/inertness benefits.
Schott AG — Borosilicate excellence
◉Products: Type I glass vials, syringes, ampoules.
◉Strength: High-purity glass for injectables.
SGD Pharma (your detailed data) — Pharma glass specialist
◉Scale: 5 plants, 7 furnaces, 1 sorting, 1 decoration; 8M+ bottles/vials output; €441M turnover (2023).
◉Strength: Global production in EU & Asia; PCR glass campaign (2024) = sustainability leadership.
West Pharmaceutical Services, Inc. — Injectable containment
◉Products: Stoppers, seals, device components; containment/closure systems.
◉Strength: Deep integration with biotech fill-finish.
Gerresheimer AG — Glass & plastic pharma
◉Products: Vials, syringes, inhalation & device packaging.
◉Strength: Broad platform across primary + devices.
Vetter Pharma International — CDMO/packaging interface
◉Products: Fill-finish, combination product final assembly/packaging.
◉Strength: Sterile operations and device kitting.
CCL Industries, Inc. — Labeling specialist
◉Products: Pharma labeling, security features.
◉Strength: Serialization-ready label systems.
Drug Plastics Group — Rigid plastics
◉Products: Bottles, closures for Rx/OTC.
◉Strength: Regulatory-grade polymers, consistency.
Becton, Dickinson and Company (BD) — Systems & devices
◉Products: Syringes, needles, systems integral to primary packaging.
◉Strength: Global standardization of syringe systems.
AptarGroup, Inc. — Drug delivery pack
◉Products: Pumps, inhaler components, nasal/ophthalmic packaging.
◉Strength: Precision dosing, patient-centric usability.
International Paper — Fiber-based secondary/tertiary
◉Products: Cartons, shippers, inserts.
◉Strength: Large-scale paperboard supply.
Comar, LLC — Specialty plastics & devices
◉Products: Bottles, closures, precision components.
◉Strength: Custom molding for regulated markets.
PCI Pharma Services
◉2024: US$ 365M investment for injectables and combination products (clinical & commercial).
◉Strength: End-to-end assembly & packaging at scale; device-combo expertise.

Get a Sample of this Report
Pharmaceutical Packaging Market
