

Plastic Surgery Market Growth From $85.98B (2025) to $217.66B by 2034 at 11.06% CAGR

Market size
Total size & trajectory
●2024: USD 77.42B
●2025: USD 85.98B
●2034: USD 217.66B
CAGR (2025–2034): 11.06%
By procedure type
●Surgical procedures: 62% share (2024); durable outcome demand in rhinoplasty, liposuction, body contouring sustains revenue base.
●Non-surgical procedures: fastest growth through 2034; injectables (toxins/fillers), lasers, skin tightening expand patient base with low downtime.
By end user
●Specialty aesthetic clinics: 55% share (2024); specialization, privacy, advanced devices concentrate spend.
●Ambulatory surgical centers (ASCs): fastest growth; same-day surgeries, cost efficiency, reduced infection risk.
By technology
●Traditional surgical techniques: 60% revenue (2024); gold-standard for complex corrections.
●Minimally invasive & energy-based tech: fastest growth; RF/ultrasound/laser/cryolipolysis/endoscopic systems compress recovery times.
Regional scale
●North America: 38% share (2024) with high spend, KOLs, early tech adoption.
●Asia Pacific: fastest CAGR on rising incomes, medical tourism, and K-beauty influence.
●Europe, Latin America, MEA: steady growth via aging demographics, tourism corridors, and improving access.
Market trends
Shift to minimally invasive: Botox/fillers/laser therapies surge; ISAPS reports ~19.1M non-surgical procedures in 2023 alongside 15.8M surgical (+5.5% YoY).
Procedure mix pivot: Liposuction leads surgical volume (2.2M cases, 2023); breast augmentation, blepharoplasty, rhinoplasty, abdominoplasty follow.
Regulatory-backed product flow: FDA approvals—Restylane Eyelight (June 2023) for tear troughs; SKINVIVE by JUVÉDERM (May 2023) for cheek smoothness—expand indications and refresh injector pipelines.
Energy-based platforms upgrade: RF microneedling + lasers (e.g., Cutera Secret DUO, 2023) deliver texture/tone improvements with modular, stackable protocols.
Demographic broadening: Rising male and millennial adoption; growing acceptance reduces stigma; social media filters/selfie culture amplify demand.
Clinic format evolution: Specialty clinics (55% share) and ASCs lead with concierge workflows, bundled pricing, and shorter stays.
Digital front doors: Virtual consults, 3D/AR visualization, and mobile post-op check-ins improve conversion and adherence.
Medical tourism corridors: Korea, Thailand, Mexico, Turkey, and India attract price-sensitive patients for standardized procedures.
Implant innovation: Biocompatible, form-stable implants and IDEAL/“structured” options emphasize safety and natural feel.
Combination therapy protocols: Toxin + filler + energy devices + skincare sequences offer incremental, natural results with fewer downtimes.
10 deep AI roles & impacts
●Outcome simulation: AI-powered 2D/3D morphing personalizes expectations, improving consent quality and conversion.
●Treatment planning: ML models optimize incision placement, implant sizing, lipo volumes, and sequence timing to reduce revisions.
●Risk stratification: Predictive analytics flag DVT/infection/anesthesia risk using EHR + imaging + lifestyle inputs.
●Imaging triage: AI reads facial/body scans to quantify symmetry, texture, laxity, and fat distribution for objective baselines.
●Intra-op guidance: Computer vision assists with plane identification and device energy dosing; robotic aids stabilize motions.
●Inventory intelligence: Forecasts toxin/filler turns, laser tips, and implant SKUs to cut stockouts and write-offs.
●Revenue cycle optimization: NLP automates documentation, coding for reconstructive indications, and denial analytics.
●Patient acquisition: Look-alike modeling and sentiment analysis refine marketing, lowering cost per booked consult.
●Post-op monitoring: App-based photo checks with AI wound assessment detect seroma/infection early, prompting tele-follow-ups.
●Quality benchmarking: De-identified multi-center data trains models comparing techniques, devices, and providers for continuous improvement.
Regional insights
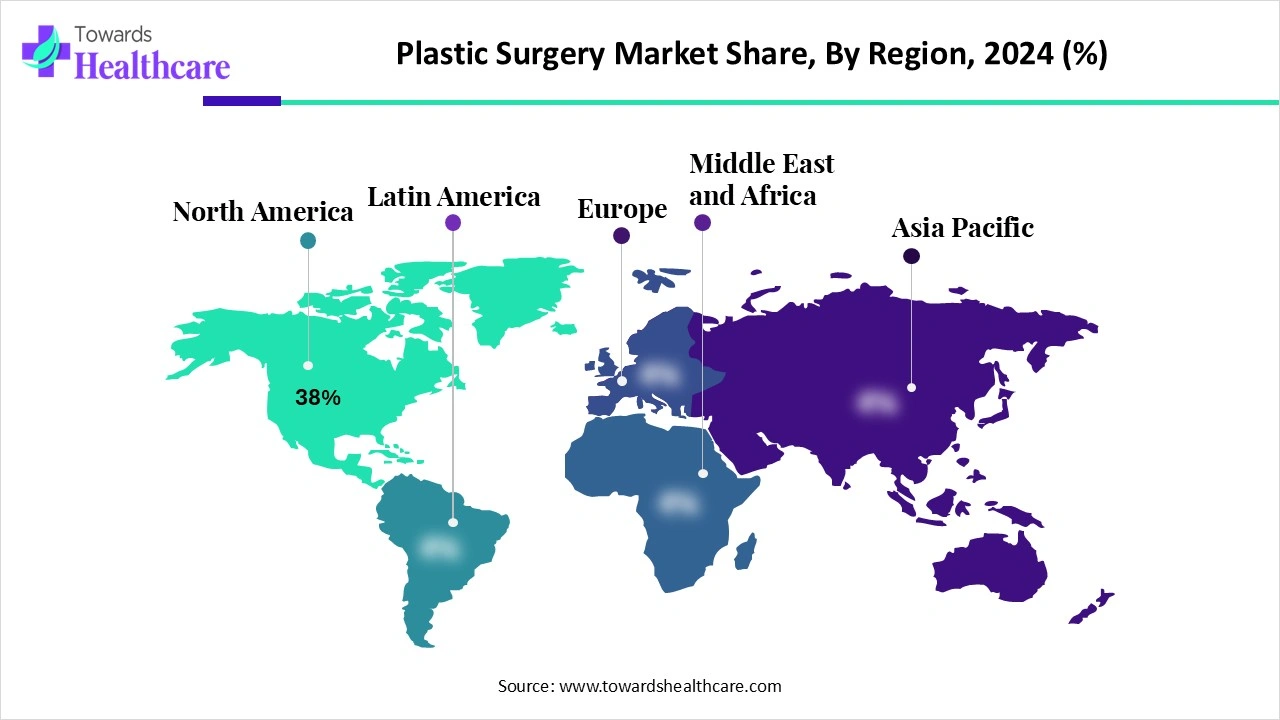
North America (38% share, 2024)
Drivers: High disposable income, insurer financing for reconstructive needs, dense KOL networks, and device availability.
Procedure mix: Strong injectables and body contouring; breast aesthetics and mommy makeovers remain core.
Channel dynamics: Corporate DSOs/MSOs scale specialty clinics; ASCs expand block time for high-throughput surgeons.
Asia Pacific (fastest CAGR)
Demand engines: K-beauty, social media aesthetic ideals, and rising middle-class spend.
Tourism: Korea/Thailand hub for facial contouring, rhinoplasty, and skin lasers; competitive pricing + high quality.
Localization: Preference for subtler, natural results; fast adoption of energy-based devices and skincare maintenance cycles.
Europe
Mature standards: Strong regulation, board certification clarity; steady growth in anti-aging injectables.
Tourism & access: Spain, Germany, Italy active in cross-border care; clinic clusters with multilingual staff.
Demographics: Aging population sustains eyelid, face/neck lifts; prevention-focused toxin/filler regimens rise.
Latin America
Cultural affinity: Brazil and Mexico anchor high surgical volumes (body contouring, gluteal shaping).
Price arbitrage: International patients blend tourism with procedures; branded surgeons elevate destination appeal.
Device adoption: Growing RF/laser use in premium urban clinics; financing plans widen access.
Middle East & Africa
Premium hubs: UAE/Saudi premium centers emphasize privacy, bundled post-op hotel recovery.
Patient profile: Younger, high-spend consumers; non-surgical first, surgical upgrades later.
Capacity build-out: Import reliance for devices; training partnerships expand certified provider base.
Market dynamics (integrating given data)
Drivers
Rising aesthetic focus & anti-aging demand: Social media + celebrity influence lift volumes; ISAPS +5.5% in 2023.
Tech advances: Minimally invasive & energy-based tech accelerating; FDA approvals (2023) feed injector pipelines.
Access models: Specialty clinics (55% share) and ASCs streamline care, reduce cost/time, and improve experience.
Restraints
High procedure costs: Limited reimbursement for cosmetic procedures restricts lower-income adoption.
Workforce & training gaps: Skilled surgeon/device-operator availability varies by region.
Regulatory heterogeneity: Cross-border differences in product approvals and advertising rules add friction.
Opportunities
AI, robotics, 3D simulation: Precision + personalization reduce revisions and elevate satisfaction.
APAC & tourism: Fastest regional CAGR via rising incomes, K-beauty pull, and destination clinics.
New indications/devices: Tear trough (Restylane Eyelight) and skin quality (SKINVIVE) expand recurring revenue.
Risks
Safety & ethics: Over-treating, counterfeit products, and unqualified providers can erode trust.
Macroeconomics: Elective spend is sensitive to interest rates and consumer confidence.
Top 10 companies
Allergan Aesthetics (AbbVie)
Products: BOTOX, JUVÉDERM family incl. SKINVIVE, CoolSculpting.
Overview: Global aesthetics leader across toxins, fillers, body contouring.
Strength: Broadest injector portfolio, training ecosystems, strong brand equity.
Johnson & Johnson (Mentor & Codman Neuroscience)
Products: Mentor breast implants/expanders; adjunct surgical tools.
Overview: Tier-1 surgical presence; standardized implant systems.
Strength: Quality reputation, surgeon trust, global supply reliability.
Galderma
Products: Dysport (toxin), Restylane fillers incl. Eyelight, skincare adjacencies.
Overview: Pure-play dermatology/aesthetics with hyaluronic acid leadership.
Strength: Continuous line extensions, indication breadth, injector education.
Merz Aesthetics
Products: Xeomin (toxin), Belotero, Radiesse; energy devices in select markets.
Overview: Neuromodulator + biostimulatory filler expertise.
Strength: Natural-look positioning, longevity data, clinic partnerships.
Sientra, Inc.
Products: Breast implants, reconstructive solutions.
Overview: Focused breast aesthetics platform in the U.S.
Strength: Patient-safety messaging, surgeon-centric service.
GC Aesthetics
Products: Implants/expanders; surgical accessories.
Overview: Europe-anchored implant vendor with multi-brand reach.
Strength: Portfolio depth across sizes/shapes; competitive pricing.
Teoxane Laboratories
Products: Teosyal HA fillers; skincare synergy.
Overview: Swiss R&D-driven filler specialist.
Strength: Gel rheology expertise; natural outcomes; injector training.
Sinclair Pharma
Products: Ellansé (biostimulatory), Silhouette Soft (threads).
Overview: Collagen-stimulating portfolio for longer-lasting lift/volume.
Strength: Differentiated, longevity-focused solutions.
InMode Ltd.
Products: RF platforms (BodyTite, FaceTite, Morpheus8).
Overview: Minimally invasive RF contouring and skin tightening.
Strength: Procedure economics for clinics; celebrity awareness.
Cynosure (Hologic)
Products: Laser/energy devices (Picosure, TempSure, Icon).
Overview: Multi-application platforms for pigment, hair removal, texture.
Strength: Diverse indications; service footprint; strong capital-equipment brand.

Get a Sample of this Report
Plastic Surgery Market
