

Single Cell Analysis Market Growth, Shares and Latest Updates 2025 - 2034

Market size
Anchor datapoints (provided):
◉2024 market size: USD 5.19B.
◉2025 market size: USD 6.16B.
◉2034 projected market size: USD 29.15B.
◉Reported CAGR (2025–2034): 18.74% (report figure).
Growth multiples & verification:
◉2024 → 2034 growth multiple: 29.15 / 5.19 ≈ 5.62× overall.
◉2025 → 2034 growth multiple: 29.15 / 6.16 ≈ 4.73×.
(Note: computing the implied CAGR from 6.16 → 29.15 over 9 years yields 18.85% by strict exponential math; the report rounds/quotes 18.74% — both indicate very rapid expansion.)
Absolute increments (illustrative):
◉Increase 2024 → 2025: +USD 0.97B (18.7% year-over-year growth).
◉Total absolute increase 2025 → 2034: +USD 23.0B (majority of value creation occurs across 2026–2034).
Value-drivers by revenue type (high-level):
◉Consumables (reagents, kits, beads, plates) already largest revenue contributor in 2024 — recurring revenue with high gross margins and predictable replacement cycles.
◉Instruments (sequencing platforms, flow cytometers, microfluidic hardware, HCS microscopes) are capital-intensive but forecast to grow fastest by CAGR as adoption expands and prices / footprint change.
◉Data analysis & downstream software (bioinformatics pipelines, multi-omics integration) contribute increasing share due to high value per sample and premium software licensing/analysis services.
Market maturity segmentation (temporal):
◉Early commercial scale (2024–2027): strong consumables revenue; instrument upgrades in center labs; pilot AI/bioinformatics.
◉Scale adoption (2028–2034): instrument installations broaden (hospitals, CROs), software/analysis becomes a substantial revenue stream and service layer.
Market trends
Consolidation & strategic partnerships (2024–2025):
◉2024–2025 saw multiple collaborations and M&A-adjacent moves (e.g., Illumina acquiring Fluent BioSciences — strengthens multiomics & single-cell offering; Roche partnering for SBX sequencing) — trend: upstream platform vendors horizontally integrate single-cell workflows.
Geographic expansion and distribution partnerships:
◉Companies expand into Asia Pacific (Singleron partnership with Bioscreen in Oct 2024; Parse + SCRUM in April 2025) — trend: distributors + local vendors to accelerate adoption in research markets.
Funding and scaleups in single-cell multomics:
◉Startups raising capital (Atrandi Biosciences $25M, Feb 2025) — trend: venture capital backs single-cell multiomics, capsule technologies and alternative library preps.
Microfluidics & droplet innovations:
◉Picodroplet and picodroplet-based microfluidic partnerships (Premas Life Sciences + Sphere Bio, May 2025; Sphere Fluidics product launches Jan 2025) indicate the trend toward higher throughput, lower cost per cell, and operational extraction methods.
Automation and throughput focus:
◉BD releasing robotics-compatible reagent kits (Oct 2024) and other vendors launching high-throughput 3D/automation friendly products (Inventia RASTRUM Allegro, Feb 2025) — trend: sample-prep automation to scale experiments and reduce operator variability.
AI + Genomics collaborations:
◉Partnerships such as NVIDIA + Illumina (Jan 2025) point to a trend: embedding AI/ML into multi-omics interpretation, accelerating clinical translation and drug discovery.
Clinical translation emphasis:
◉Government and clinical trials focus (UK government oncology initiatives, Oct 2024) — trend: regulators & public funding pushing single-cell tech toward diagnostic/therapeutic pipelines.
Product launches accelerating capability:
◉Bruker Beacon Discovery (Apr 2025), Scale Biosciences launches (Feb 2025), Sphere Fluidics Early Access (SLAS2025) — trend: vendors rapidly iterating to expand single-cell live analysis, multiomics, and accessible RNA workflows.
AI role & impact on the single-cell market
1. Data volume & complexity problem → AI necessity
◉Single-cell experiments (scRNA-seq, scATAC, multiomics) produce millions of data points per study; traditional statistics are insufficient for pattern discovery, so advanced AI/ML is required to reduce dimensionality, denoise, and discover biologically relevant clusters.
2. Preprocessing & denoising
◉AI models (autoencoders, variational methods) are used to impute dropouts, correct batch effects, and harmonize multi-center datasets — improving signal/noise and enabling meta-analyses across cohorts.
3. Integration of multi-omics at single-cell resolution
◉Deep learning enables joint modeling of transcriptome + epigenome + proteome signals per cell, identifying regulatory relationships and causal paths that single-modality analyses miss.
4. Cell-type annotation and reference mapping
◉Supervised & semi-supervised classifiers trained on large labeled atlases automatically annotate cell types and states, speeding sample interpretation and reducing manual curation.
5. Spatial transcriptomics + image analysis fusion
◉AI performs image segmentation, spot deconvolution, and links spatial patterns to single-cell profiles; convolutional neural nets interpret histology and local microdomain signals to map cellular neighborhoods.
6. Predictive modeling for treatment response & biomarker discovery
◉Models trained on single-cell signatures can predict drug sensitivity, immune checkpoint responses, and evolutionary trajectories of tumors—driving translational research and precision oncology.
7. Automation & workflow orchestration
◉AI schedules and optimizes robotic sample prep, recommends QC thresholds, and directs adaptive experiments (e.g., prioritize cells for deeper sequencing based on preliminary analysis).
8. Compression & storage optimization
◉Learned compression reduces storage and accelerate retrieval for massive single-cell datasets, reducing infrastructure costs for large centers.
9. Quality control, anomaly detection & reproducibility
◉Anomaly detection flags poor libraries, doublets, or contamination; AI-driven QC increases reproducibility and reduces wasted runs.
10. Democratization via turnkey cloud analysis
◉Partnerships (e.g., NVIDIA + Illumina) enable packaged AI analysis stacks that non-bioinformatics labs can use—turning complex single-cell output into actionable reports.
11. Regulatory & explainability challenges
◉For clinical use, AI models must be explainable; investment in interpretable models and validation datasets is required before classifiers become diagnostic tools.
12. Commercial implications
◉AI adds high-margin software & services revenue (licensing, cloud processing), shifts vendor differentiation from hardware to analytics, and creates recurring revenue streams.
13. Future frontier — generative & causal models
◉Generative models may predict unseen cell states, suggest perturbations for validation, and map causal gene regulatory networks — unlocking hypothesis generation at scale.
Regional insights
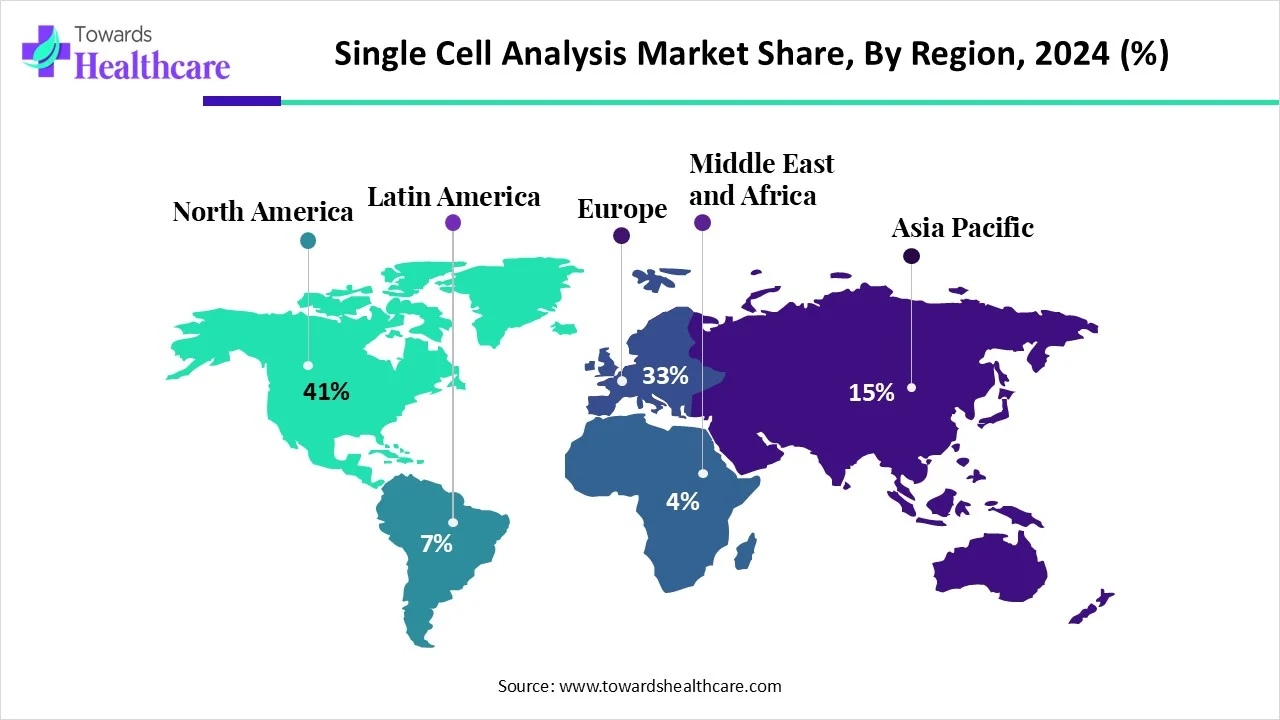
North America (Leader — 41% market share in 2024)
Ecosystem & demand drivers:
◉Dense concentration of pharmaceutical/biotech R&D centers and academic research — fuels demand for both instruments and consumables.
Technology leadership & early adoption:
◉Home to many platform vendors and early adopters; higher per-lab budgets allow instrument upgrades and adoption of high-throughput workflows.
Clinical translation & regulatory pathway:
◉Active clinical trials and diagnostic translation pathways accelerate adoption of clinically-oriented single-cell assays.
◉Market implication: Region remains the primary revenue pool and a testing ground for premium, integrated platforms and AI analytics.
Asia Pacific (Fastest growing region)
Investment & capacity building:
◉Significant public & private investment in genomics and life science infrastructure (China, Japan, India, Korea).
Distribution & local partnerships:
◉Strategic distributor alliances (e.g., Singleron + Bioscreen; Parse + SCRUM) localize supply chains and reduce time-to-market.
Cost sensitivity & volume use case:
◉Large research cohorts, high patient volumes, and lower per-test price expectations push vendors to cheaper consumable costs and scalable microfluidic platforms.
◉Market implication: Rapid growth potential; vendors focusing on low-cost, scalable consumables and regional support will capture share.
Europe
Genomics & personalized medicine emphasis:
◉Strong governmental and academic investment in personalized medicine and immunotherapy.
Regulatory caution & clinical validation:
◉Emphasis on robust clinical validation and data protection regimes influences the design of clinical single-cell products and analytics.
◉Market implication: Premium markets for validated, compliant workflow solutions and partnerships with national health systems.
Latin America
Emerging research networks & capacity building:
◉Growing symposiums and local initiatives (Single Cell LATAM Symposium, Aug 2024) indicate rising awareness.
Challenges & opportunities:
◉Lower immediate purchasing power but growing ambitions for precision medicine create demand for training, partnerships, and lower-cost consumables.
◉Market implication: Opportunity for service providers, regional distributors, and low-capex consumable models.
Middle East & Africa (MEA)
Early stages with targeted investments:
◉Select centers of excellence and government initiatives; adoption often via partnerships and centralized labs.
◉Market implication: Focus on centralized service labs and collaborations rather than broad instrument installations initially.
Market dynamics
Driver — Rising incidence of cancer & chronic disease
◉Single-cell resolves intra-tumor heterogeneity, tracks immune microenvironment, and identifies rare subclones — strong use cases drive consumable and instrument demand.
◉Supporting data: Cancer segment dominated application share (report), and North America led by research investment.
Driver — Advances in sequencing & microfluidics
◉Decreasing per-cell cost and higher throughput (NGS integration, microfluidic droplet tech) increase experiment volume — both instruments and consumables benefit.
Restraint — High cost of instruments & reagents
◉Capital expenditure for sequencers, flow cytometers, and high-content imagers and the recurrent cost of reagents pose access barriers to smaller labs.
◉Impact: Slows adoption in cost-sensitive regions; favors centralized service models or contract research organizations (CROs).
Restraint — Need for bioinformatics & skilled personnel
◉Interpreting single-cell data requires advanced bioinformatics; shortage of trained staff and complex pipelines creates friction and increases TCO (total cost of ownership).
Opportunity — AI & software monetization
◉AI + cloud analytics create recurring revenue via software licenses, managed analysis, and interpretive reports — an opportunity for vendors to diversify beyond hardware sales.
Opportunity — Clinical diagnostic and therapeutic translation
◉As trials and government programs (e.g., UK cancer detection trials) validate clinical utility, single-cell assays could move into diagnostic workflows — a high-value opportunity if regulatory hurdles are cleared.
Opportunity — Consumables as predictable revenue
◉Consumables dominance in 2024 highlights the opportunity for vendors to lock customers into long-term consumable supply agreements and subscription models.
Market structural dynamics:
◉Platform vendors vs. niche innovators: Large vendors (Illumina, Thermo Fisher, Roche) integrate vertically, while nimble startups push novel chemistries and microfluidic workflows; partnerships/acquisitions are common.
◉Service model expansion: Centralized single-cell sequencing services and CRO partnerships expand access without capital buy-in for end users.
Top companies
10x Genomics
◉Product focus: Chromium single-cell platforms (high-throughput scRNA-seq, multiomes).
◉Overview: Pioneer in droplet-based high-throughput single-cell library prep and multiomics.
◉Strength: Market recognition, large user base, ecosystem of protocols and reference datasets.
BD (Becton Dickinson)
◉Product focus: Flow cytometers, sample prep consumables, reagent kits.
◉Overview: Legacy instrument vendor expanding into automated reagent kits for high-throughput workflows.
◉Strength: Robust instrument installed base, automation partnerships, regulatory experience.
Bio-Rad Laboratories
◉Product focus: Cell analysis instruments, reagents and consumables for cell biology workflows.
◉Overview: Established maker of lab instrumentation and assay kits.
◉Strength: Broad life-science portfolio and channel reach.
Illumina
◉Product focus: Sequencing platforms and now single-cell acquisitions (e.g., Fluent BioSciences).
◉Overview: Dominant NGS vendor integrating single-cell library prep and throughput solutions.
◉Strength: Sequencing market leadership, scale, integration capability for multiomics workflows.
Qiagen
◉Product focus: Sample prep, reagents, bioinformatics solutions for molecular workflows.
◉Overview: Provides end-to-end sample processing kits; moving into single-cell compatible solutions.
◉Strength: Strong reagents business and global distribution.
Thermo Fisher Scientific
◉Product focus: Sequencing systems, mass spec, flow cytometry accessories, reagents.
◉Overview: Broad life-science instrument portfolio supporting single-cell workflows.
◉Strength: Global sales & service, integrated offerings across sample prep → analytics.
Mission Bio, Inc.
◉Product focus: Single-cell DNA sequencing (tumor heterogeneity, CRISPR screens).
◉Overview: Niche leader in single-cell DNA mutation profiling and precision oncology workflows.
◉Strength: Clinical-oriented single-cell DNA platform and partnerships (e.g., Integrated DNA Technologies).
RareCyte, Inc.
◉Product focus: Rare cell detection (circulating tumor cells) and imaging cytology platforms.
◉Overview: Specialized in rare cell detection workflows and imaging analysis.
◉Strength: Niche clinical and translational strength for liquid biopsies.
Takara Bio Inc.
◉Product focus: Library prep kits, PCR systems, reagents for single-cell and sequencing workflows.
◉Overview: Reagents and kits provider with strong presence in Asia and global coverage.
◉Strength: Reagent reliability and kit portfolio; good ties to academic researchers.
Ancilia Biosciences / CYTENA / Others (BGI, PacBio, Oxford Nanopore, Roche)
Products & strengths:
◉BGI / Novogene: High-throughput sequencing services and NGS capacity.
◉PacBio / Oxford Nanopore: Long-read sequencing options enabling different single-cell genomic analyses.
◉Roche: Diagnostics & sequencing partnerships (SBX) for clinical scale; strengths in clinical validation and distribution.
◉CYTENA: Microfluidic handling and single-cell dispensing systems, enabling automated workflows.
◉Strengths: each brings complementary capabilities — long reads, sequencing capacity, clinical pipelines, or microfluidic automation.

Get a Sample of this Report
Single Cell Analysis Market
