

Small Molecule API Market Reports 2035 with a CAGR of 6.1%.

Small Molecule API Market Size
Base and near-term scale (2025–2026)
• 2025 reported market size: US$206.9B.
• 2026 actual/recorded value: US$219.52B — an absolute increase of US$12.62B year-over-year indicating continued near-term demand momentum.
Long-term projection (2035 target)
• Forecast for 2035: ≈US$374.03B, reflecting structural growth in chronic-disease therapies, oncology small molecules, and expanded global manufacturing capacity.
Compound annual growth
• CAGR 2026–2035 = 6.1% — implies the market roughly doubles over ~11 years (consistent with the 2026→2035 projection).
Revenue concentration and leadership
• North America accounted for ~45% of market revenue in 2024 (hence a dominant revenue base into 2025–2026).
Segment revenue drivers (size drivers rather than application breakdown)
• Branded/innovator APIs contributed a majority share (~55% in 2024) — this elevates average ASPs and margins across the market.
• Small-molecule organic APIs dominated volume/value (~82% in 2024), anchoring the market’s bulk revenue.
Growth pockets with outsized impact on size
• Oncology small molecules (32% of 2024 revenue) and generics expansion (fastest growth among product types) together push volume and addressable market size.
Geographic growth skew
• Asia-Pacific expected fastest regional CAGR — a material contributor to the 2035 projection via capacity expansions and cost-competitive production.
Role of CDMOs and contract manufacturing on scale
• Expanding CDMO capacity and reshoring investments (by large pharmas) increase regional production throughput — directly increasing market monetized volumes.
High-value subsegments lift average revenue per unit
• HPAPIs, sterile small-molecule injectables, and peptidomimetics add higher ASPs and regulatory complexity — increasing market value beyond mere volume growth.
Policy & investment effects on size
• National programs (e.g., India PLI for KSMs/DI/API) and country-level incentives accelerate local production capacity and therefore contribute to market size expansion.
Market Trends
Shifting sourcing strategies (insourcing + CDMO mix)
• Large pharma invests in internal capacity to reduce supply risk, while simultaneously outsourcing specialized or overflow work to CDMOs — creating a two-tier manufacturing demand.
Oncology focus and targeted small molecules
• Oncology led with ~32% revenue (2024) — trend: continued R&D and approvals for small-molecule inhibitors raise long-term demand.
Generic/merchant API ramp
• Generic/merchant APIs identified as fastest-growing product type — price competition drives volume and market share gains for low-cost producers.
Rapid growth of HPAPIs & cytotoxics
• High demand and specialized containment needs propel facility investments and higher per-kg revenue.
Regional capacity buildout (APAC, Brazil, GCC, MEA)
• APAC fastest growing; Brazil, GCC, and MEA push to localize manufacturing — diversifying global supply.
Technology adoption (continuous manufacturing, flow chemistry)
• Advanced synth and continuous processing raise yields, reduce cost per kg, and shorten lead times — improving competitiveness.
Regulatory & legislative accelerants
• Examples like Germany’s Medical Research Act (Oct 30, 2024) speed clinical development and can accelerate API demand tied to local trials.
Sustainability and green chemistry
• Increasing emphasis on greener synthetic routes to reduce waste, regulatory risk, and long-term costs.
Vertical integration & M&A
• Larger companies and CDMOs consolidate capacities and capabilities to offer end-to-end services from process R&D → commercial supply.
Digitalization & AI in process optimization
• AI and model-based platforms (e.g., Lonza’s Design2Optimize) accelerate scale-up and reduce time-to-clinic/commercial — see AI section below for deep impacts.
10 ways AI impacts / roles in the small-molecule API market
Route-and-process design optimization
• AI predicts optimal synthetic routes and reaction conditions (solvent, catalyst, temperature), reducing the number of lab experiments and accelerating process R&D timelines.
Model-based scale-up & manufacturability scoring
• Machine models evaluate candidate molecules for manufacturability and scale-up risk, enabling early go/no-go decisions and guiding investments before expensive pilot runs.
Predictive yield and impurity profiling
• AI tools forecast expected yields and impurity profiles for alternate routes, prioritizing pathways that minimize costly purification steps and regulatory burden.
Process control and real-time optimization
• Integration of AI with PAT (process analytical technologies) enables closed-loop control for real-time adjustments (e.g., feed rates, residence time), improving consistency in continuous manufacturing.
Analytical method development and QC acceleration
• AI speeds up method development for HPLC/LC-MS and helps automate peak deconvolution and impurity identification, shortening release times and testing bottlenecks.
Predictive maintenance and capacity utilization
• Machine learning forecasts equipment failures and optimizes maintenance windows, increasing effective throughput for cGMP plants and reducing unplanned downtime.
Regulatory dossier and CMC generation support
• AI assists in collating chemistry, manufacturing and control (CMC) documentation, auto-suggesting standard text/analyses and flagging gaps — reducing time to file.
Supply-chain risk forecasting
• AI models combine supplier, geo-political and logistics data to produce risk scores, enabling dynamic sourcing strategies (e.g., pivot to nearer suppliers, build buffer stocks).
Green-chemistry route discovery
• Generative models propose synthetic pathways that reduce hazardous reagents, solvent volumes, and waste streams — supporting sustainability goals and regulatory acceptability.
Drug candidate prioritization tied to manufacturing economics
• Integrated AI scoring frameworks combine pharmacology and manufacturability (cost per kg, time to clinic) so decision-makers prioritize candidates that balance efficacy with realistic production economics.
Regional insights
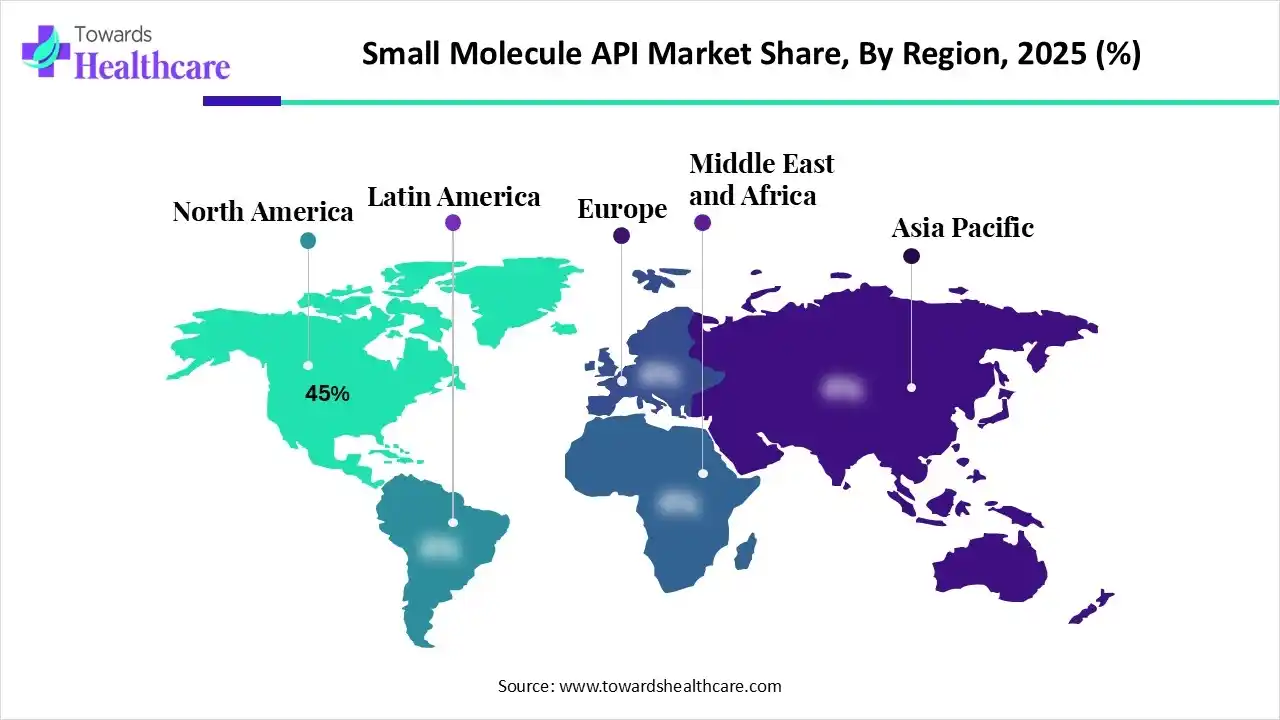
North America (dominant; 45% revenue in 2024)
• Market character: High ASPs, strong R&D pipeline, rapid adoption of advanced manufacturing (continuous, HPAPI containment).
• Drivers: Large biotech/pharma R&D spend, regulatory sophistication, clinical trial density.
• Implication: Demand for high-quality, complex APIs and CDMO partnership models — makes NA a profitable, innovation-led market.
Asia-Pacific (fastest-growing region)
• Market character: Rapid capacity additions, cost competitiveness, growing regulatory maturation.
• Drivers: Investments in pharma manufacturing, government schemes (e.g., India’s PLI), strong generic manufacturing base.
• Implication: APAC will drive volume growth and take increasing share in generic and intermediate supply chains.
Europe (established, quality-driven)
• Market character: Strong regulatory standards, advanced manufacturing, emphasis on sustainability and process innovation.
• Drivers: Policy support for R&D (e.g., Germany’s Medical Research Act), existing industrial base.
• Implication: Europe remains a hub for high-end, regulated production and innovation in HPAPIs and continuous processing.
Latin America (emerging; Brazil focal point)
• Market character: Growing local manufacturing capability, supportive policies for GMP upgrades.
• Drivers: Domestic investments, collaborations with global CDMOs.
• Implication: Regional self-sufficiency improves; Brazil can become a regional API export hub.
Middle East & Africa (MEA) and GCC
• Market character: Nascent but rapidly investor-backed; focus on capacity and regulatory reform.
• Drivers: Sovereign investments (Saudi, UAE), healthcare modernization.
• Implication: Long-term diversification of global supply; potential specialized export corridors for niche APIs.
India (special callout due to “Make in India”/PLI)
• Market character: Large generic capabilities, drive to become low-cost global supplier.
• Drivers: PLI funding (₹6,940 crore), domestic pharma ecosystem, strong chemical intermediates base.
• Implication: Accelerated capacity for KSMs/DIs/APIs, greater export competitiveness, and improved resilience for global supply chains.
Market dynamics
Demand dynamics
• Chronic diseases and oncology approvals (50 NMEs example note) sustain long-term API demand; generics keep volume high post-patent cliffs.
Supply dynamics
• Dual trend: reshoring by big pharma + expansion of CDMOs → increases global capacity but shifts where capacity sits (more in APAC plus regional hubs in Brazil/GCC).
Price dynamics
• Branded APIs command higher ASPs; generic competition compresses prices but expands volume — net market value rises because of added higher-value subsegments (HPAPI, sterile injectables).
Regulatory & policy dynamics
• Policy changes (e.g., Germany Medical Research Act) and incentive schemes (India PLI) alter national competitive positions and speed pipeline-to-market timelines.
Technology dynamics
• Adoption of continuous manufacturing, flow chemistry and AI increases productivity and lowers costs per unit, changing unit economics across suppliers.
Competition dynamics
• Legacy large pharmas, global CDMOs, and cost-competitive Asian players form a layered competitive structure — each competes on quality, price, or specialization.
Vertical integration dynamics
• MNCs expanding internal CDMO capabilities (e.g., Pfizer CentreOne model) change the supplier landscape — some capacity becomes captive, some outsourced.
Investment dynamics
• Large CAPEX flows into HPAPI facilities, analytical labs (e.g., SK Pharmteco), and model-based platforms (e.g., Lonza) — this raises structural capacity and capability.
Risk dynamics
• Geopolitical, trade and quality incidents can rapidly shift sourcing — buyers adopt multi-sourcing and risk modelling.
Sustainability & compliance dynamics
• Environmental regulations and green chemistry demands force process re-engineering and capital investments that favor larger, well-capitalized players.
Top 10 companies
Lonza Group
• Product/Offerings: CDMO services for small molecules and biologics, model-based platform (Design2Optimize).
• Overview: Leading Swiss CDMO with global footprint and integrated development→commercial capabilities.
• Strength: Advanced process platforms, end-to-end CDMO scale and early adoption of model-based process acceleration.
Catalent Inc.
• Product/Offerings: Formulation, scale-up, commercial manufacturing (APIs & finished dose solutions).
• Overview: US CDMO specializing in development solutions and drug-delivery technologies.
• Strength: Integrated development + packaging + global supply chain for finished dosage and API needs.
Cambrex Corporation
• Product/Offerings: Process chemistry, API development and manufacturing.
• Overview: Focused API/CDMO specialist with expertise in complex small molecules.
• Strength: Agility in process development and mid-scale commercial supply.
Bachem
• Product/Offerings: Peptide synthesis, GMP peptide APIs and small-molecule manufacturing.
• Overview: Swiss manufacturer with a global reputation for peptide/oligo APIs.
• Strength: Peptide and specialty API manufacturing excellence and GMP compliance.
Siegfried Group
• Product/Offerings: Development, manufacturing and packaging for APIs and finished products.
• Overview: Swiss CDMO offering end-to-end services across regulated markets.
• Strength: Integrated solutions and European regulatory familiarity.
Divi’s Laboratories
• Product/Offerings: Generic APIs, intermediates, KSMs.
• Overview: India-based API manufacturer with broad generic portfolio.
• Strength: Cost-competitive manufacturing and strong supply to generics market.
Aurobindo Pharma
• Product/Offerings: Generic APIs, formulations and global supply to generics markets.
• Overview: Large Indian generics and API producer with global distribution.
• Strength: Scale, cost advantage, and broad product portfolio.
Dr. Reddy’s Laboratories
• Product/Offerings: Innovator + generic APIs, formulations, and CDMO services.
• Overview: Integrated Indian pharma with both domestic and international reach.
• Strength: Balanced innovator/generic capabilities and regulatory experience in multiple markets.
Merck KGaA (MilliporeSigma / Life Science business)
• Product/Offerings: Custom/contract API manufacturing (small molecules & HPAPIs), catalog APIs and lab materials (EMPROVE®).
• Overview: Centuries-old life-science leader with extensive lab consumables → CDMO pipeline.
• Strength: Scale, R&D infrastructure, HPAPI expertise, and integrated supply from lab reagents to commercial API.
Pfizer (Pfizer CentreOne)
• Product/Offerings: Internal API supply plus Pfizer CentreOne CDMO API & intermediates, specialty/complex APIs and sterile injectables.
• Overview: Large innovator pharma with an embedded CDMO arm that services both internal and external demands.
• Strength: Unmatched regulatory trust, complex chemistry capabilities, and secure supply backed by large-cap pharma resources.

Get a Sample of this Report
Small Molecule API Market
